
Australia has a long history of financial innovation. The 1980s brought ATMs and EFTPOS, followed by telephone banking, internet banking and BPAY in the 1990s. By the early 2000s, many Australians could manage their finances without ever visiting a bank branch.
FinTech as we know it today began to develop more significantly during the 2010s. Initiatives such as Stone & Chalk and ASIC’s Innovation Hub created a stronger environment for financial technology start-ups, while the launch of the New Payments Platform in 2018 enabled near real-time payments around the clock.
These developments helped establish Australia as a serious participant in the global FinTech industry. Today, Deloitte Access Economics estimates that the sector contributes approximately $13.6 billion directly to the Australian economy and employs more than 50,000 people. With the right investment and policy settings, that contribution could reach $37 billion annually within a decade.
After years of rapid growth, however, the industry is entering a more mature phase. The focus is shifting from expansion towards commercial sustainability, regulatory compliance, institutional partnerships and the ability to operate at scale. This shift is particularly relevant to the future of Islamic finance.
A growing global market
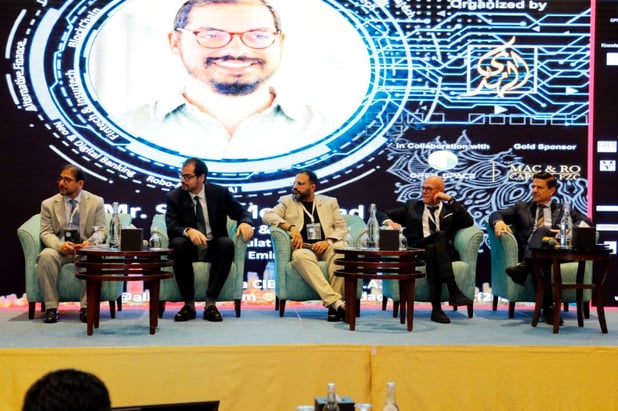
Islamic FinTech is becoming an increasingly significant part of the global financial technology sector.
According to the Global Islamic FinTech Report 2025/26, the market was valued at an estimated US$198 billion in 2024–25 and is projected to reach US$341 billion by 2029. The report identifies 484 Islamic FinTech companies operating across 41 countries. dinarstandard.com
Activity is concentrated in markets such as Saudi Arabia, Malaysia, Indonesia and the United Arab Emirates, where Islamic finance benefits from established institutions, strong consumer demand and, in some cases, dedicated regulatory frameworks.
Australia is in a different position. We have a sophisticated conventional financial system, strong consumer protections and well-developed financial technology capabilities, but our Islamic finance sector remains relatively small. Only four Australian companies are included among the 484 businesses identified in the report.
Nevertheless, these businesses demonstrate that Australia’s Islamic FinTech opportunity extends across several areas.
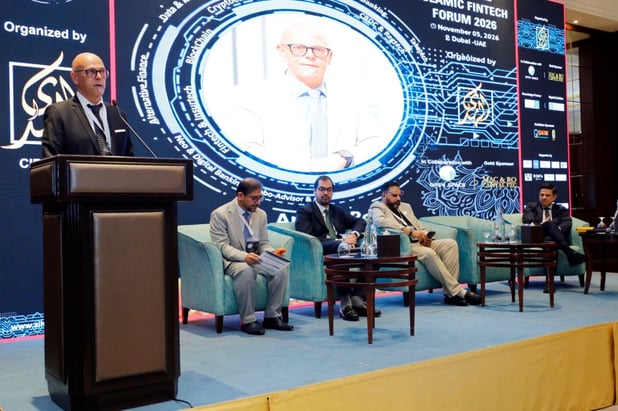
Bless Payments operates in digital payments and international remittances, helping address the need for faster, more affordable and transparent cross-border transfers. This is particularly relevant to Australia’s multicultural communities and our strong connections with Southeast Asia, the Middle East and other international markets.
HalalStocks focuses on Shariah-compliant investment strategies and stock screening. Digital screening tools can help Muslim investors identify companies that meet Islamic investment principles and participate in financial markets without compromising their beliefs.
Invest Wholesum connects responsible investors with financing opportunities for small and medium-sized businesses. Technology-enabled investment platforms can provide alternative pathways to capital while giving investors access to opportunities aligned with their values.
Marhaba, through the MRHB Network, is exploring Shariah-compliant digital assets, decentralised finance and the tokenisation of real-world assets. While this area remains relatively new, it could expand access to asset-backed investments and Islamic financial products across international markets. It must, however, develop alongside appropriate regulation, governance, risk management and Shariah oversight.
Together, these businesses show that Islamic FinTech in Australia is not confined to one product. It already spans payments, wealth management, business financing and digital assets.
The opportunity in faith-based superannuation
One of the most significant opportunities for Islamic FinTech in Australia lies in superannuation.
Australia has one of the world’s largest retirement savings systems, with approximately $4.8 trillion in total assets as at June 2026. www.apra.gov.au Superannuation is compulsory for most working Australians and plays an important role in their long-term financial security.
Its compulsory nature also raises an important question: what happens when the available investment options do not align with an individual’s religious beliefs?
This was one of the issues we sought to address when establishing Salaam and developing Islamic superannuation in Australia. Our objective was to demonstrate that Shariah-compliant retirement savings could operate within Australia’s existing superannuation framework.
Our experience has reinforced three important observations. There is genuine demand for investment options that reflect members’ values. Specialist providers do not necessarily need to replicate the entire infrastructure of a conventional superannuation fund. And partnerships with established financial institutions can provide access to the technology, administration, compliance systems and investment capabilities required to operate effectively.
Salaam’s approach combines institutional infrastructure and global investment capabilities with specialist Islamic investment expertise and Shariah oversight.
This reflects a broader trend within FinTech. Innovation is increasingly about working with established financial institutions rather than attempting to replace them. Through these partnerships, Islamic finance providers can focus on their distinctive strengths: their values, specialist expertise, product design and understanding of the communities they serve.
As Australia’s Muslim population grows, so too does the potential demand for faith-based superannuation and investment products.
Addressing the barriers to growth
Australia must also be realistic about the challenges ahead.
Islamic FinTech operates within a broader regulatory system that was not originally designed around Islamic financial structures. This can create complexity in areas such as taxation, asset-backed finance and products that avoid conventional interest-bearing arrangements.
The relatively small size of the Australian Islamic finance sector can also make it difficult to attract capital, develop competitive products and achieve economies of scale. Greater consumer awareness, financial education, professional expertise and access to investment will all be necessary.
Technology alone cannot resolve these challenges. Progress will require cooperation between financial institutions, regulators, investors, technology businesses and Islamic finance providers.
Australia is unlikely to replicate the Islamic finance ecosystems of Malaysia or the Gulf states. Our market is different. However, that does not prevent us from developing a successful model of our own—one that integrates specialised Islamic financial products into a sophisticated and highly regulated conventional financial system.
Building the next phase of Islamic FinTech
The next phase of Islamic FinTech in Australia will be defined less by the number of new companies entering the market and more by the quality, accessibility and reach of the solutions they deliver.
Australia already has much of the infrastructure and financial expertise required. The emergence of Bless Payments, HalalStocks, Invest Wholesum and Marhaba shows that Australian businesses are beginning to apply these capabilities to a broader range of Islamic financial needs.
The next challenge is achieving scale.
Superannuation provides one practical example of how Islamic investment principles can operate within a major Australian financial system, supported by institutional partnerships and technology. There are opportunities to make these products more accessible, transparent, diversified and competitive.
The broader opportunity extends beyond superannuation to payments, business finance, investment management, digital assets and access to international markets.
As Islamic FinTech continues to grow internationally, Australia has an opportunity to play a more substantial role. By building on the financial technology capabilities we already possess, we can make Islamic finance a more established and accessible part of Australia’s broader financial system.
No Comments Yet
Let us know what you think